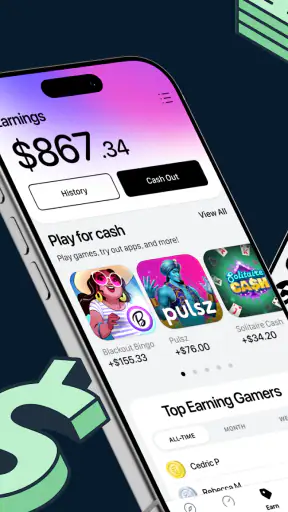
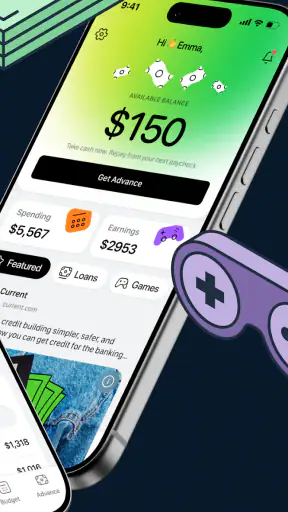
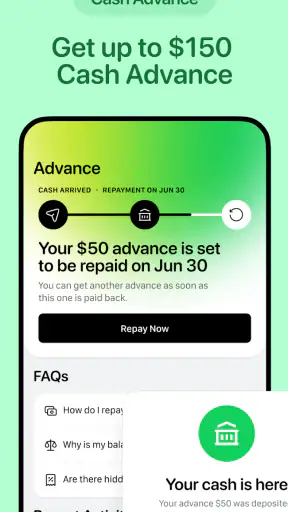
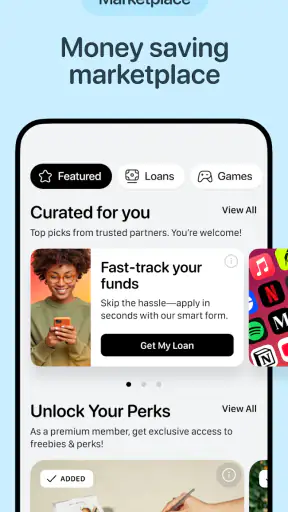
When an unexpected bill lands between paydays, the appeal of True Finance: Cash Advance is easy to understand. It is a free finance app from JoinTrueDev built around quick access to cash, with the store summary presenting it as “Fast Cash, No Credit Check.” I found that its main strength is convenience: it gives people a focused place to explore a cash-advance option instead of making them search through a broad banking app or fill out a long general-purpose financial tool.
That convenience needs to be viewed carefully, though. A cash advance is not the same thing as extra income, and the right choice depends on the terms shown during your own application. I would treat this app as a short-term emergency tool, not as a regular way to cover a monthly budget gap. Used with a clear repayment plan, it may be useful. Used repeatedly without checking the full cost and timing, it can make the next payday even tighter.
How I would use True Finance from the first screen to a decision
The basic workflow is straightforward. I would install the app, read each screen rather than rushing through it, and enter only information I am comfortable sharing for the application process. The store lists the app as free, but that does not automatically mean every cash-advance offer has no cost. Those are two different questions: the app may not charge for downloading it, while an advance may still have its own fees, repayment conditions, or other requirements.
That distinction is the first practical habit I recommend. Before accepting anything, I would look for the total amount I would repay, the expected repayment date, and any optional service or expedited-transfer charge displayed in the offer. If the app presents several choices, I would compare the complete repayment amount rather than focusing only on the amount deposited. A smaller advance with a clearer repayment schedule can be safer than taking the maximum available.
The app is listed for Everyone, which makes it broadly accessible from an age-rating perspective, but that rating should not be confused with approval eligibility. Finance products can still involve identity checks, account requirements, location restrictions, or other conditions. I would not assume that the “no credit check” wording guarantees approval or removes every form of review. It is better understood as a promise about one part of the assessment, not as a promise that every applicant receives money.
For a realistic example, imagine that my car needs an urgent repair two days before payday. I might use the app to investigate whether a small advance could cover the repair, then compare the repayment date with my next paycheck. If repayment would leave me unable to pay rent, utilities, food, or another essential bill, I would stop there. The fact that an application is quick does not make the underlying obligation harmless.
I also like to keep the purpose of the advance narrow. Paying a one-off medical, transport, or household expense is easier to evaluate than using borrowed cash for everyday shopping. Before applying, I would write down the exact amount needed and avoid adding a cushion simply because the app offers one. That simple step limits the chance of turning a temporary problem into a larger repayment.
What the app is good at—and where the normal banking route is better
Compared with asking a traditional bank for a small personal loan, True Finance may feel less intimidating and more focused on immediate needs. A bank loan can involve a longer application, a formal credit process, and a repayment structure designed for a larger amount. This app’s appeal is the possibility of handling a smaller, urgent request through a phone.
The trade-off is that a bank, credit union, employer advance, or carefully managed overdraft may offer a more predictable cost in some situations. Existing customers may also have access to clearer account support or a lower-cost option through their normal provider. I would compare those alternatives before accepting an offer here, especially if I need more than a single payday bridge.
A useful comparison is not “Which app is fastest?” but “Which option leaves me with the most manageable next month?” True Finance can be convenient when speed and simplicity matter, yet convenience should not outweigh transparent terms. If an alternative gives me a fixed repayment schedule that fits my budget, I would prefer it even if the application takes longer.
Settings and permissions I would review before applying
Experienced use starts with checking the phone settings around the app, not just tapping through the application. I would review notification access and decide whether reminders are useful or distracting. A repayment reminder can prevent an avoidable missed date, but I would not allow a flood of alerts to push me into making a rushed decision.
I would also inspect the app’s permission requests as they appear. A finance app should have a clear reason for anything it asks to access. If a permission seems unrelated to the application, I would pause and investigate through the app’s own explanation or my device settings before granting it. The safest workflow is to provide what is necessary for the service while keeping unrelated personal information restricted.
On a shared or borrowed phone, I would be especially careful. I would use the device’s screen lock, avoid leaving application pages open, and sign out where the app provides that option. I would not save sensitive financial details in an unsecured notes app or send screenshots of an offer through casual messaging. These are small precautions, but finance information deserves more care than an ordinary shopping account.
Another setting worth checking is the device’s battery and background-data behavior. If notifications are delayed because the operating system limits the app, I would not rely on a reminder as my only repayment system. I would place the date in my regular calendar as well, using the exact date and amount shown in the final agreement. A separate reminder is more reliable than assuming every app alert will arrive on time.
I would also review the app’s current version after installation. True Finance is listed as version 10.6.0 and supports Android 7.0 or later, so older Android devices may still be compatible. Compatibility alone does not guarantee a smooth experience, however. If the phone is heavily outdated, modified, or short on storage, I would avoid completing a sensitive financial application until the device is stable and protected.
Repeatable habits that make the process faster without making it careless
The fastest safe pattern is preparation. I would have my basic personal and banking information ready, use a stable connection, and complete the application when I can read every screen. Doing this at the kitchen table is better than applying while walking, commuting, or dealing with a stressful emergency. Speed matters, but attention matters more when the result is a financial obligation.
I would keep a small written checklist beside me: amount needed, total repayment, repayment date, transfer timing, and what happens if the date changes. If the offer does not make one of those points clear, I would not fill the gap with assumptions. I would look for an in-app explanation or support route before continuing. This habit is more valuable than memorizing where buttons are because the terms can matter more than the interface.
For repeat users, I would avoid treating a previous approval as evidence that the next application will be identical. Each request can be evaluated on its own circumstances, and the available amount or conditions may differ. I would start a fresh comparison each time, even if the earlier experience was smooth. Familiarity is useful for navigation, but it can also encourage careless acceptance.
I would also avoid submitting multiple applications across several cash-advance services at once. When money is urgent, it is tempting to apply everywhere and choose the first response. That approach makes it harder to track agreements, notifications, and repayment dates. A better sequence is to calculate the need, compare realistic alternatives, and keep a record of the one option I actually accept.
One practical workflow is to separate “checking eligibility” from “accepting funds.” I would first explore the available information, then close the app and review my budget before committing. That short pause helps me notice whether repayment depends on money that is already assigned to another bill. It also reduces the pressure created by a fast approval screen.
I would never share login codes, verification messages, or banking credentials with another person claiming to help complete the process. If someone contacts me outside the app and asks for those details, I would stop and use an official in-app support path instead. A legitimate-looking financial conversation can still create serious account risk when sensitive codes are disclosed.
Limits that matter more than the headline promise
The phrase “no credit check” can be attractive, especially to someone who has been rejected by conventional lenders. Still, it should not be read as “no questions asked.” An application may involve other forms of verification, and approval is never something I would assume before seeing the actual result. The app can make the process easier to start, but it cannot remove the need to judge affordability.
The biggest limitation is structural: a cash advance moves money forward rather than solving the reason I am short. If my income does not cover regular expenses, taking an advance every pay cycle can create a repeating hole. I would consider the app unsuitable for rent, debt consolidation, ongoing groceries, or any expense that appears month after month without another plan to address it.
Another point is timing. “Fast” does not necessarily mean instant in every situation. Bank processing, verification, weekends, account issues, or other conditions can affect when money is available. I would not use a cash advance for a deadline that cannot tolerate uncertainty, such as a same-hour payment, unless the app clearly confirms the transfer timing and I have a backup.
I would also pay attention to repayment mechanics. If the repayment is scheduled automatically, I would make sure the linked account will contain enough money on that date. An automatic debit can be convenient, but it can also trigger overdraft problems if I forget about it. If the app offers a way to review or manage the schedule, I would do that early rather than waiting until the due date.
Privacy is another reason to slow down. Finance applications handle sensitive personal and account information, so I would read the privacy and authorization screens before agreeing. I would not install an unofficial copy or rely on a download shared through an unknown source. The legitimate listing identifies JoinTrueDev as the developer, and I would verify that developer name in the store before installing.
The app has an average rating of 4.4 from around 47 thousand ratings, with roughly 4.2 thousand written reviews, and it has passed the one-million-install mark. Those figures suggest that many people have tried it, but they do not predict my approval, my offer, or my experience with support. I would read recent user comments for recurring issues while remembering that individual financial situations differ widely.
Who should use it, and who should choose something else
I see True Finance as a possible fit for an adult who needs a modest, one-time bridge, understands the repayment date, and has dependable income arriving soon. It may also suit someone who wants to explore an alternative to a conventional loan without starting with a broad bank application. The value is greatest when the need is specific and the repayment is already accounted for.
I would steer away from it if I had no confirmed income date, if my account was already overdrawn, or if I needed to borrow to repay another advance. I would also choose a different option if I wanted a larger amount, a long repayment period, financial counseling, or a fixed loan structure that could be compared line by line. In those cases, a credit union, bank, employer program, or nonprofit financial service may be more appropriate.
People who dislike sharing financial information through mobile applications should also think carefully before proceeding. A desktop banking relationship or in-person provider may offer more reassurance and human explanation. The convenience of a phone-based application is not valuable if it makes me uncomfortable enough to accept terms without understanding them.
Parents and caregivers should remember that an Everyone content rating does not turn the app into a child-oriented financial product. I would keep access to any finance application private and would not let a child apply using another person’s information. The rating describes general content suitability, not permission to use a financial service without meeting its requirements.
My verdict after building a careful routine around it
True Finance: Cash Advance is most convincing when treated as a tightly controlled emergency option rather than a financial habit. I appreciate the focused purpose, the free download, and the possibility of a simpler route than a conventional loan application. Its popularity—more than one million installs—also means it is not an obscure experiment, although popularity should never replace reading the actual offer.
My preferred routine would be simple: install the official app, check the developer name, review permissions, enter the smallest necessary amount, compare the complete repayment terms, and record the due date outside the app. I would then ask whether repayment still works after rent, food, transport, utilities, and existing obligations are covered. If the answer is no, I would not proceed.
The app’s current version is 10.6.0, and its Android requirement begins at version 7.0, which makes it accessible to many older devices. Even so, I would keep the operating system and security protections current whenever possible. A finance app should be used on a device I trust, with a screen lock and careful control over notifications and permissions.
In the end, I would recommend it to a friend only with a condition: use it for a defined short-term gap, not as a substitute for a balanced budget. The most important feature is not the speed of the application; it is knowing exactly how repayment will affect the next payday. If that calculation works and the terms are clear, this free finance app may be worth considering. If the numbers are already tight, a slower but more structured alternative is the wiser choice.


